
India Construction Chemicals Market Size, Share, Trends and Forecast by Type, Application, and Region, 2026-2034
India Construction Chemicals Market Size, Share, Trends & Forecast (2026-2034)
The India construction chemicals market grew from USD 2.62 Billion in 2025 to USD 2.88 Billion in 2026 and is projected to reach USD 4.76 Billion by 2034, exhibiting a CAGR of 6.49% during 2026-2034. Accelerating infrastructure development, rapid urbanization, and strong government support for residential and non-residential construction are the primary growth drivers shaping the market.
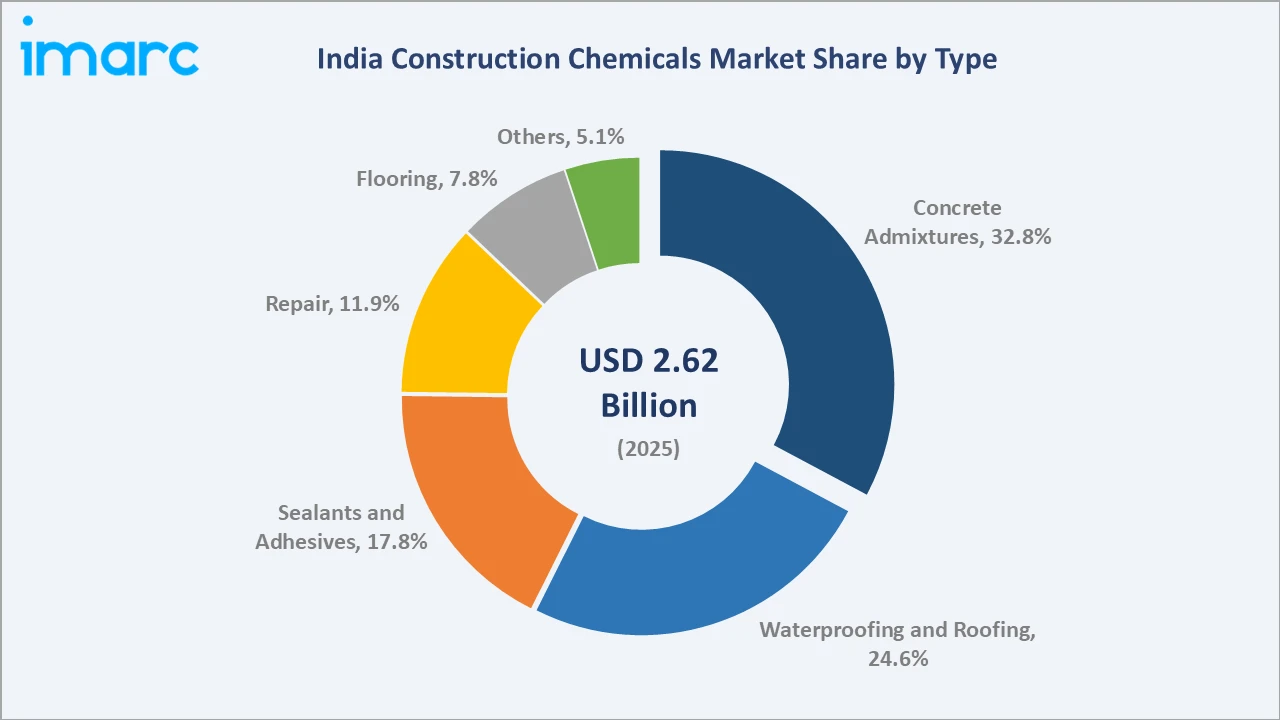
Concrete admixtures lead the type segment at 32.8%, non-residential dominates the application segment at 62.4%, and West and Central India commands 31.7% of regional share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 2.62 Billion |
| Market Size (2026) | USD 2.88 Billion |
| Forecast Market Size (2034) | USD 4.76 Billion |
| CAGR (2026-2034) | 6.49% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | West and Central India (31.7%, 2025) |
| Second Largest Region | South India (27.8%, 2025) |
| Leading Type | Concrete Admixtures (32.8%, 2025) |
| Leading Application | Non-Residential (62.4%, 2025) |
The India construction chemicals market size increased from USD 1.92 Billion in 2020 to USD 2.62 Billion in 2025 and is estimated to reach USD 2.88 Billion in 2026. Anchored at USD 3.59 Billion in 2030, the forecast to USD 4.76 Billion by 2034 reflects continued government infrastructure spending, an active residential housing pipeline, and rising awareness of performance-enhancing chemical solutions among contractors and developers.
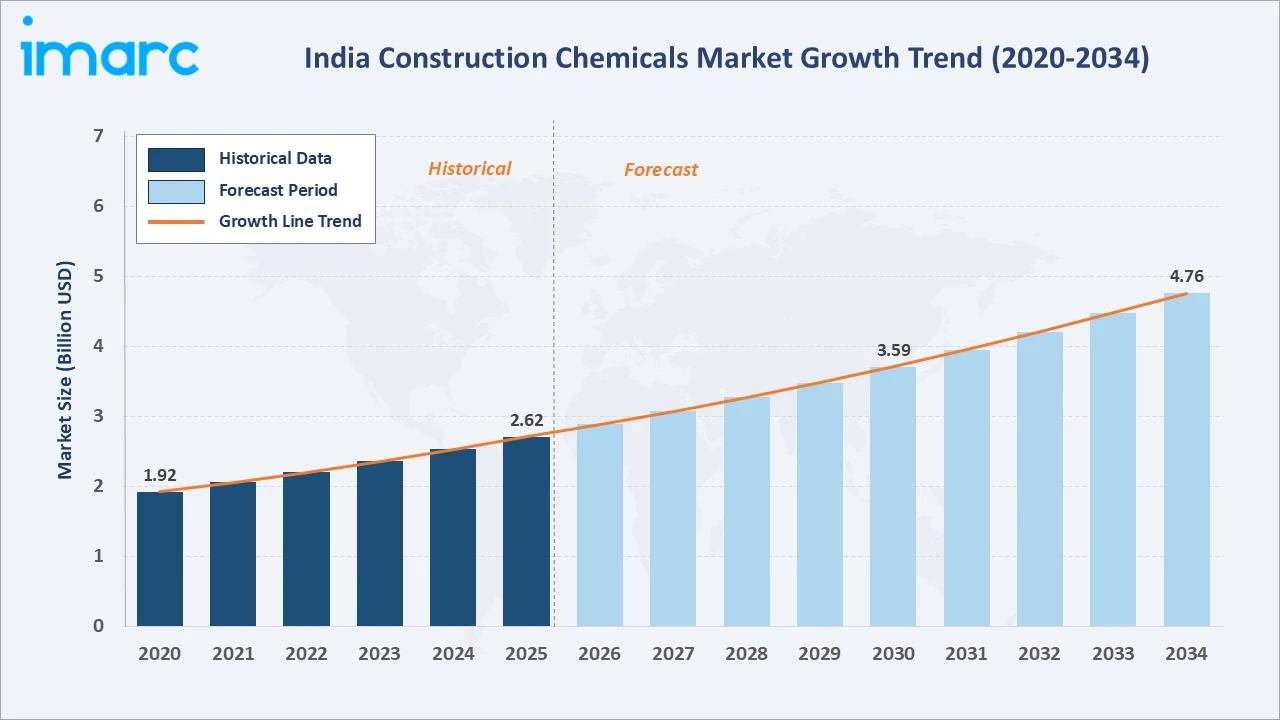
To get more information on this market, Request Sample
CAGR trajectories across type and application sub-segments, together with regional patterns, show waterproofing and roofing and residential expanding faster than the overall 6.49% market CAGR, driven by intensifying infrastructure projects, growing residential construction, and increased specification of moisture-protective and surface-enhancing chemical solutions.
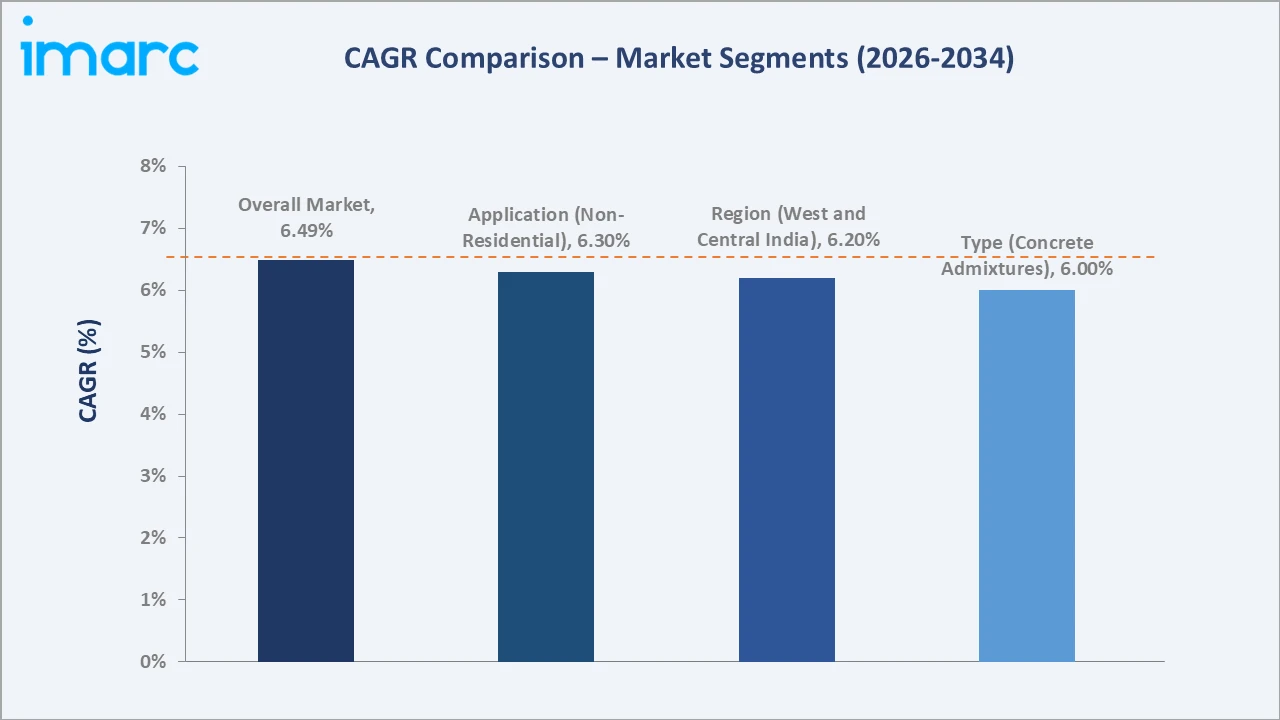
Executive Summary
The India construction chemicals market expanded from USD 2.62 Billion in 2025 to an estimated USD 2.88 Billion in 2026. The industry encompasses a broad spectrum of specialty chemical products, including concrete admixtures, waterproofing compounds, sealants, adhesives, repair mortars, and flooring systems, applied to improve structural durability, workability, and surface performance. Robust infrastructure investment, expanding urban housing programs, and increasing adoption of advanced chemical formulations across large-scale construction projects are reshaping the competitive landscape.
Non-residential dominates the application segment at 62.4% in 2025, reflecting the scale and chemical intensity of institutional, industrial, and infrastructure construction activity underway nationally. Concrete admixtures command 32.8% of the type segment in 2025, driven by growing use in large-scale infrastructure and high-rise construction. West and Central India leads regional share at 31.7%, anchored by strong construction activity in Maharashtra and Gujarat.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Type | Concrete Admixtures – 32.8% share (2025) |
| Second Largest Type | Waterproofing and Roofing – 24.6% share (2025) |
| Leading Application | Non-Residential – 62.4% share (2025) |
| Second Largest Application | Residential – 37.6% share (2025) |
| Leading Region | West and Central India – 31.7% share (2025) |
| Second Largest Region | South India – 27.8% share (2025) |
| Top Companies | Sika AG, Pidilite Industries Ltd., Compagnie de Saint-Gobain S.A., Mapei S.p.A. |
Key Analytical Observations Expanding On the Data Above:
- Concrete admixtures at 32.8% are supported by large volumes of ready-mix concrete in infrastructure and high-rise construction, where workability, setting time, and compressive strength enhancement are standard specification requirements.
- Waterproofing and roofing at 24.6% reflect intensifying application in basements, water tanks, terraces, tunnels, and metro rail infrastructure, where moisture protection is a critical structural requirement.
- Non-residential dominance at 62.4% reflects the high chemical intensity of commercial buildings, industrial plants, transport infrastructure, and institutional construction, where specialty chemicals are specified for structural longevity and performance assurance.
- Residential at 37.6% is driven by rising demand for waterproofing, tile adhesives, repair mortars, and other construction chemicals that improve building durability and protect homes from moisture damage.
- West and Central India share at 31.7% benefit from industrial development, urban infrastructure expansion, and sustained construction activity across commercial and residential projects.
India Construction Chemicals Market Overview
Construction chemicals refer to specialty chemical products applied during the construction, renovation, or maintenance of buildings and infrastructure to improve performance characteristics including structural strength, durability, waterproofing, adhesion, and aesthetic finish. They encompass concrete admixtures, waterproofing agents, sealants, adhesives, repair compounds, and flooring systems that extend the service life and enhance the functionality of construction structures across residential, commercial, and infrastructure applications.
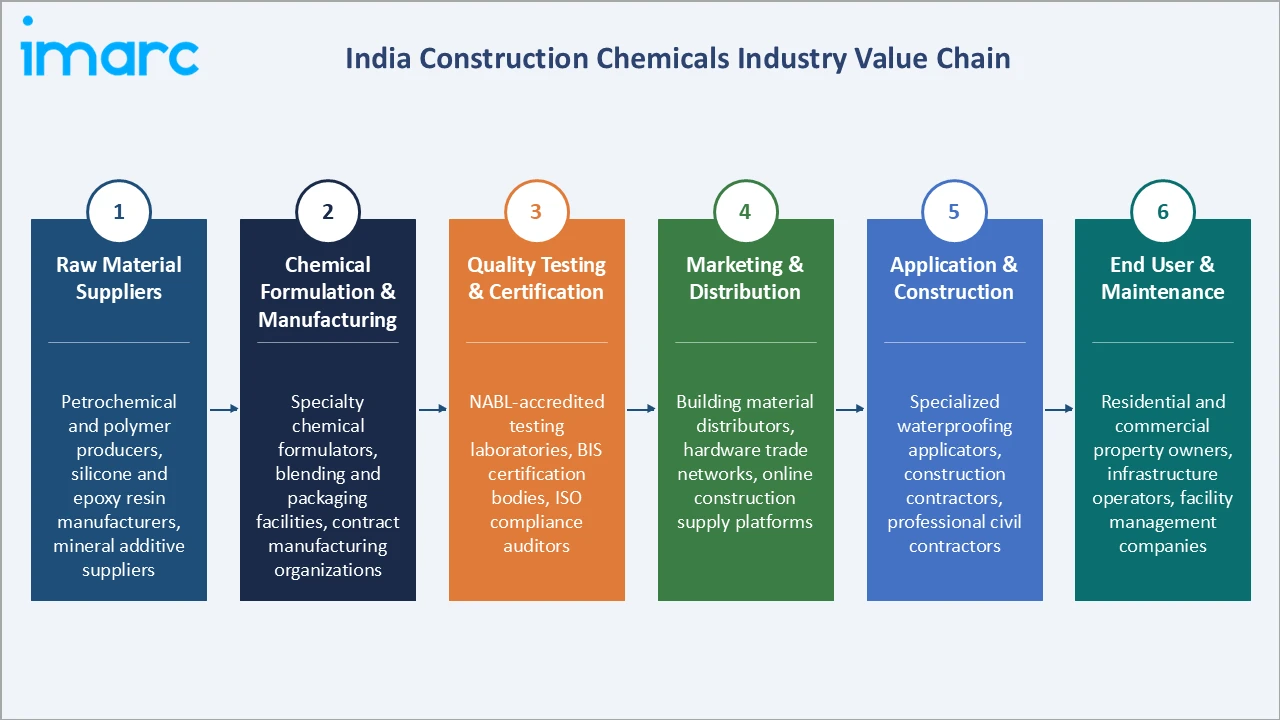
The India construction chemicals ecosystem integrates raw material and polymer suppliers, specialty chemical manufacturers, third-party testing and certification bodies, trade distributors and wholesale networks, professional applicators and contracting firms, and end users across residential, commercial, industrial, and infrastructure segments. Growing adoption of pre-engineered building systems, increasing specification by architects and engineers, and expanding government infrastructure programs are broadening market reach across urban and semi-urban regions.
Market Dynamics
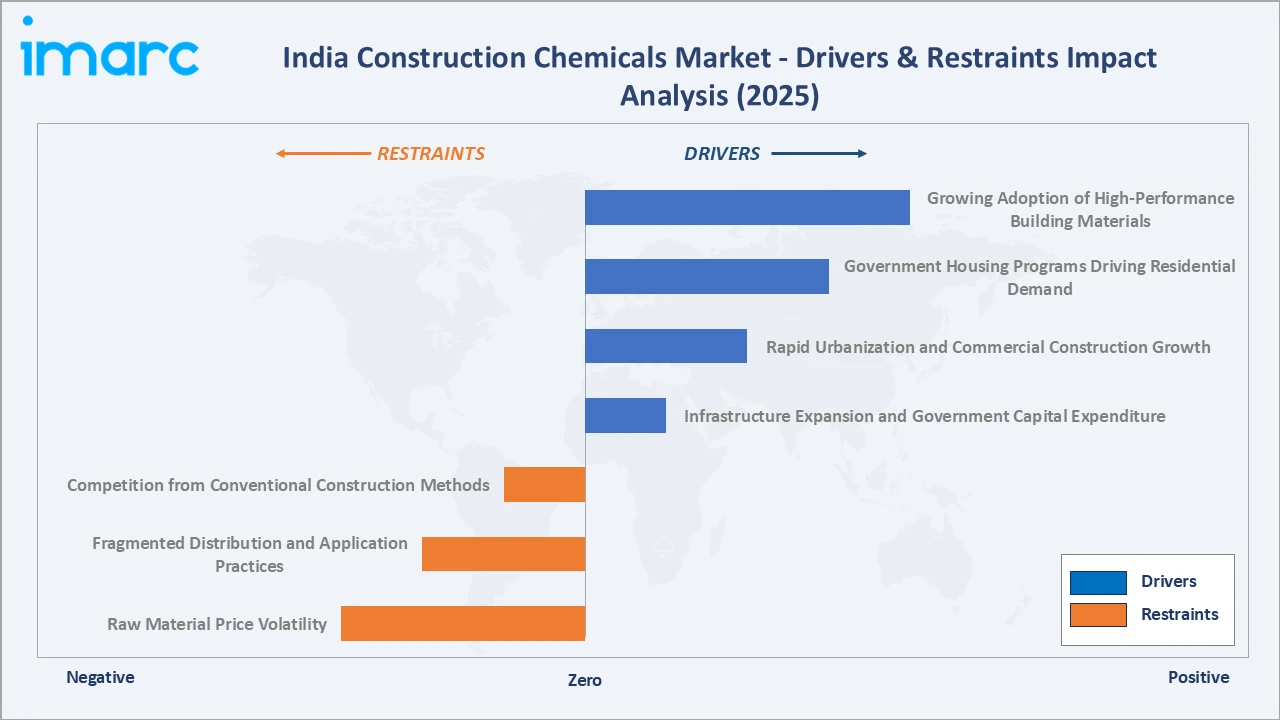
To evaluate market opportunities, Request Sample
Market Drivers
- Infrastructure Expansion and Government Capital Expenditure: Sustained growth in national highways, expressways, metro rail, airports, and port infrastructure under government programs is creating large-scale demand for concrete admixtures, waterproofing compounds, and repair chemicals. In August 2025, the Indian Prime Minister, Shri Narendra Modi launched two significant National Highway initiatives with a total investment of nearly INR 11,000 Crore in Rohini, Delhi.
- Rapid Urbanization and Commercial Construction Growth: India's urban population is expanding steadily, driving construction of commercial office spaces, shopping centers, hotels, hospitals, and educational institutions where advanced construction chemicals are specified for structural performance, waterproofing, and aesthetic finish. In 2024, the urban population as a percentage of the total population in India was reported at 36.87%, as per the World Bank collection of development indicators.
- Government Housing Programs Driving Residential Demand: Central and state government housing programs have sanctioned large volumes of affordable housing construction, creating consistent demand for waterproofing products, tile adhesives, sealants, and repair solutions in the residential construction segment.
- Growing Adoption of High-Performance Building Materials: Increasing contractor and developer awareness of the performance and lifecycle cost benefits of specialty chemicals, together with rising specification by architects and engineers, is accelerating adoption of admixtures, polymer-modified repair mortars, and hybrid sealants across project types, contributing to sustained growth in the construction chemicals market size in India.
Market Restraints
- Raw Material Price Volatility: Construction chemical formulations rely on petrochemical derivatives including polymers, epoxy resins, polyurethane precursors, and cellulose ethers, the prices of which are influenced by crude oil fluctuations, import duties, and global supply disruptions, introducing cost uncertainty for manufacturers and end users.
- Fragmented Distribution and Application Practices: A large share of India's construction activity takes place in the unorganized sector, where awareness of specialty construction chemicals remains limited, application quality is inconsistent, and price sensitivity restricts adoption of premium chemical solutions.
- Competition from Conventional Construction Methods: Lower-cost traditional construction approaches continue to compete with specialized chemical solutions in tier-2 and tier-3 cities and rural areas, limiting market penetration in price-sensitive construction segments.
Market Opportunities
- Green Building and Sustainable Construction: Rising adoption of green building certification standards is creating demand for low-VOC, eco-friendly, and energy-efficient construction chemical formulations, opening premium market segments for construction chemical companies in India with sustainable product portfolios.
- Smart Cities and Urban Renewal Projects: The Smart Cities Mission and AMRUT 2.0 are investing in urban infrastructure renewal and new township development, providing consistent demand for waterproofing, repair, and flooring chemicals in large-scale urban projects.
Market Challenges
- Skilled Application Labor Shortage: Optimal performance of construction chemicals requires trained applicators, and a shortage of skilled labor in the India construction sector can limit the effectiveness and adoption of advanced chemical solutions, particularly in smaller projects and tier-2 cities.
- Quality Standardization and Counterfeiting: The prevalence of sub-standard or counterfeit products in certain regional markets undermines confidence in specialty construction chemicals, creating challenges for established manufacturers competing on product quality and performance guarantees.
Emerging Market Trends
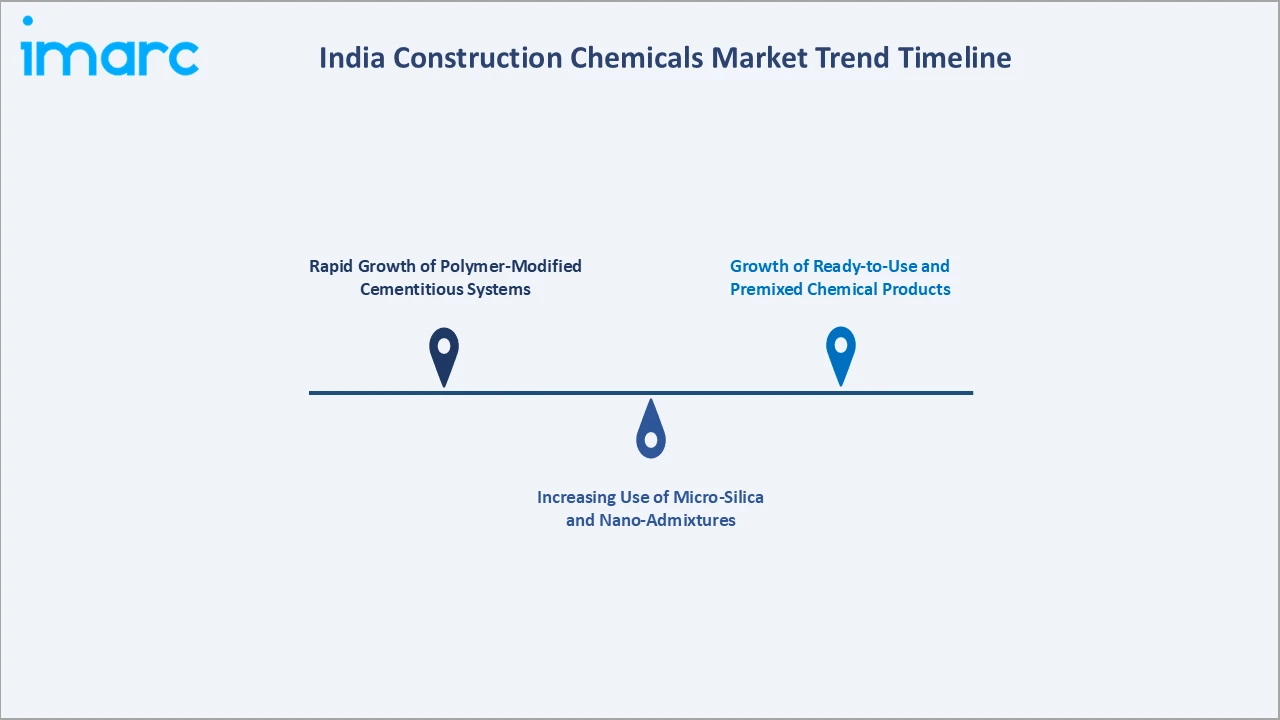
1. Rapid Growth of Polymer-Modified Cementitious Systems
Polymer-modified cement-based formulations are gaining strong traction across waterproofing, tile adhesive, and repair applications, offering enhanced bond strength, flexibility, and crack resistance compared to traditional cementitious materials. Their growing adoption in large infrastructure and commercial construction projects is reshaping product specification patterns and raising the performance benchmark for construction chemicals.
2. Increasing Use of Micro-Silica and Nano-Admixtures
Advanced concrete admixtures incorporating micro-silica, nano-silica, and carbon nanotubes are gaining adoption in high-performance concrete applications for bridges, tunnels, and high-rise buildings, improving compressive strength, impermeability, and chemical resistance. This trend is particularly evident in specialized infrastructure projects that demand ultra-high-durability structural concrete.
3. Growth of Ready-to-Use and Premixed Chemical Products
The shift toward ready-to-use, factory-premixed chemical formulations is reducing on-site application errors, improving the consistency of finished results, and accelerating project timelines. This trend is particularly evident in tile adhesive, waterproofing, and crack-filling product categories, where application simplicity directly influences contractor adoption and brand loyalty.
Industry Value Chain Analysis
The India construction chemicals value chain spans six stages, from raw material sourcing and polymer synthesis through formulation, quality assurance, distribution, and end-user application. Formulation and manufacturing, advanced testing and certification, and post-application technical services capture the highest value-add, while supply chain efficiency and distribution breadth increasingly determine competitive positioning in this cost-sensitive and specification-driven market.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Suppliers | Petrochemical and polymer producers, silicone and epoxy resin manufacturers, mineral additive suppliers |
| Chemical Formulation & Manufacturing | Specialty chemical formulators, blending and packaging facilities, contract manufacturing organizations |
| Quality Testing & Certification | NABL-accredited testing laboratories, BIS certification bodies, ISO compliance auditors |
| Marketing & Distribution | Building material distributors, hardware trade networks, online construction supply platforms |
| Application & Contracting | Specialized waterproofing applicators, construction contractors, professional civil contractors |
| End User & Maintenance | Residential and commercial property owners, infrastructure operators, facility management companies |
Vertically integrated manufacturers owning proprietary formulation technology and direct contractor relationships are positioned to capture greater value than companies reliant on third-party chemical suppliers, as technical service capabilities and brand credibility increasingly determine specification outcomes in the India construction chemicals market.
Technology Landscape in the India Construction Chemicals Industry
Advanced Polymer-Modified Formulations
Modern construction chemicals increasingly incorporate high-performance polymers including styrene-butadiene rubber (SBR), styrene-acrylate, and EVA copolymers as modifiers for cement-based systems, delivering improved flexibility, adhesion, and long-term durability across waterproofing, repair, and tile adhesive applications.
Nanotechnology in Concrete Admixtures
Nano-silica and nano-calcium carbonate additives are being incorporated into concrete admixtures to achieve ultra-high compressive strength, reduced permeability, and improved resistance to aggressive chemical environments, with growing application in specialized infrastructure projects such as bridges, ports, and underground structures.
Digital Application Monitoring and Smart Coatings
Emerging sensor-embedded coatings and digital monitoring systems are enabling real-time assessment of coating integrity, moisture ingress, and structural health in critical infrastructure assets, representing a growing frontier for high-value construction chemical applications.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Concrete Admixtures | 32.8% | 2025 |
| Application | Non-Residential | 62.4% | 2025 |
| Region | West and Central India | 31.7% | 2025 |

By Type
Concrete admixtures command a 32.8% majority share in 2025, driven by large volumes of ready-mix concrete usage in infrastructure, high-rise residential, and commercial construction where workability, setting time, and strength gain enhancement are critical. The segment benefits from rising investment in large-scale infrastructure projects and the growing adoption of high-performance concrete specifications.
To access detailed market analysis, Request Sample
Waterproofing and roofing at 24.6% in 2025 represent the second-largest segment, with demand supported by expanding infrastructure requiring below-grade and above-grade waterproofing solutions, as well as growing residential awareness of moisture protection.
By Application
Non-residential dominates the application segment at 62.4% in 2025, reflecting the high chemical intensity of commercial buildings, industrial plants, highways, bridges, metro rail, airports, and water treatment infrastructure where advanced construction chemical specifications are standard practice for structural protection and performance assurance.
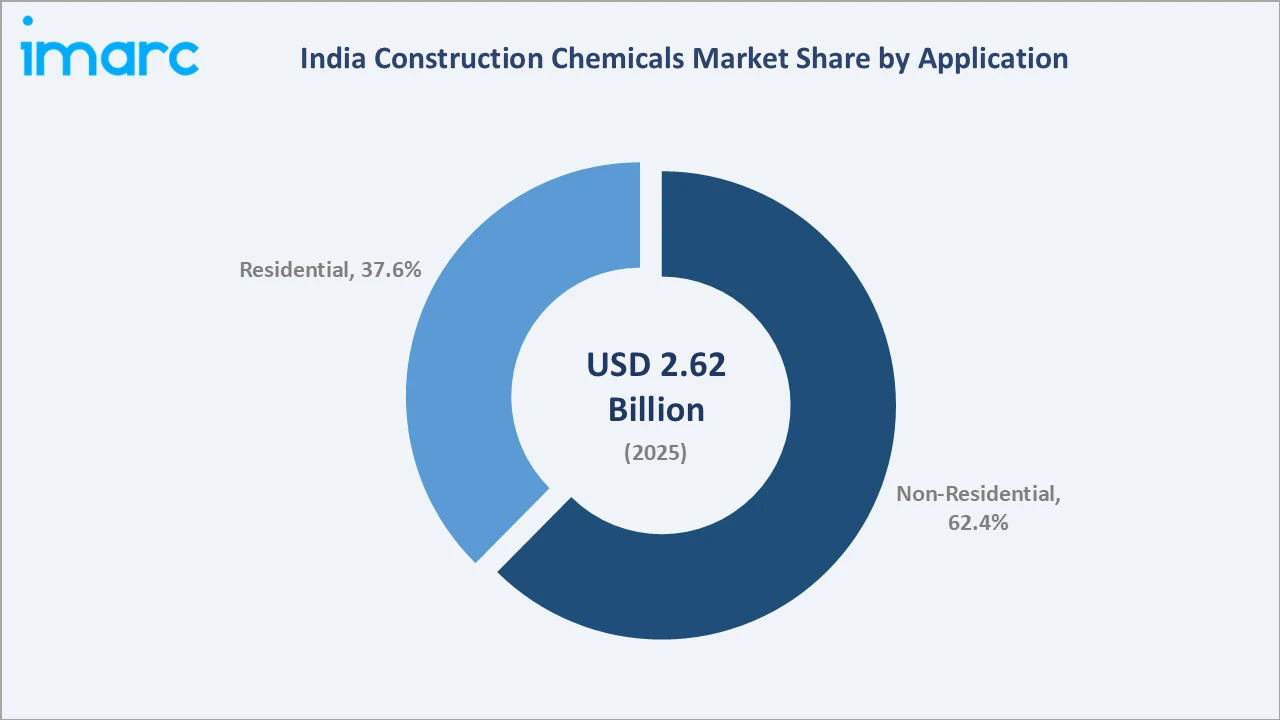
Residential at 37.6% in 2025 includes mass housing, affordable housing, and premium residential construction, with demand concentrated in tile adhesives, waterproofing compounds, sealants, and repair products. Growing consumer awareness and government housing programs are driving adoption of specialty chemical solutions for durability enhancement and aesthetic finishing in the residential segment.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| West and Central India | 31.7% | High construction activity in Maharashtra and Gujarat, strong infrastructure investment, and established distribution networks for construction chemicals |
| South India | 27.8% | Robust commercial and industrial construction, strong technology corridor development, and increasing infrastructure investment in major cities |
| North India | 24.1% | Large population base, expanding metro rail and expressway infrastructure, and government housing programs driving residential construction |
| East and Northeast India | 16.4% | Growing urbanization, expanding connectivity infrastructure under Act East Policy, and increasing government investment in industrial and residential development |
West and Central India at 31.7% in 2025 leads the regional landscape, anchored by concentrated construction activity in Maharashtra and Gujarat where large-scale infrastructure projects, commercial real estate development, and industrial construction drive consistent demand for concrete admixtures, waterproofing systems, and adhesives. Mumbai and Pune's position as major construction markets and the presence of established chemical distributors underpin the region's leadership.
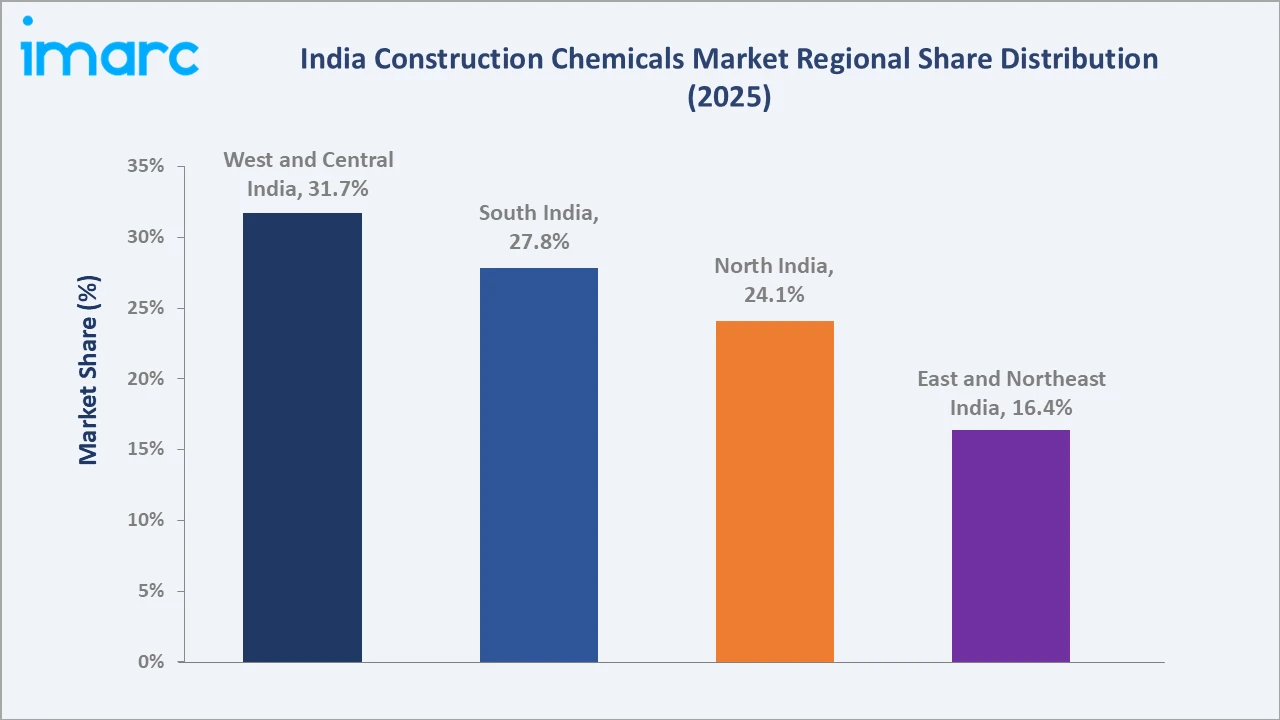
East and Northeast India, while currently the smallest regional contributor at 16.4%, is expanding steadily as accelerating urbanization and government investment in industrial parks and logistics hubs create growing demand for construction chemicals. The region represents significant untapped opportunity for manufacturers extending distribution and technical service networks into emerging construction markets.
Competitive Landscape
The India construction chemicals market is moderately concentrated, with global specialty chemical majors and domestic market leaders competing alongside regional and private-label players. Product innovation, technical service capabilities, distribution depth, and brand credibility in the specification-driven architecture and construction community serve as the primary competitive differentiators across the industry.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Sika AG | Sika | Leader | Growing market presence through expanded distributor network, technical training programs, and specialty product launches for infrastructure and building applications |
| Pidilite Industries Ltd. | Dr. Fixit | Leader | Deepening market penetration through strong brand equity, wide distribution reach, and product development for waterproofing and adhesive segments |
| Compagnie de Saint-Gobain S.A. | Weber, Fosroc | Challenger | Strengthening market reach through diversified construction solutions and specialized product offerings |
| Mapei S.p.A. | Mapei | Challenger | Strengthening commercial and industrial flooring, tile fixing, and waterproofing product lines through international expertise and local market adaptation |
Key players include Sika AG, Pidilite Industries Ltd., Compagnie de Saint-Gobain S.A., and Mapei S.p.A., among others.
Key Company Profiles
Sika AG
Sika AG is a Swiss specialty chemicals company headquartered in Baar, Switzerland, with a strong presence in the India construction chemicals market through a diverse product range covering concrete admixtures, waterproofing, adhesives, sealants, and flooring systems.
- Product Portfolio: Concrete admixtures, waterproofing membranes, structural adhesives, joint sealants, and industrial flooring solutions.
- Recent Developments: Sika AG continues to strengthen its presence in India by expanding its manufacturing operations, broadening its distribution network, and growing its range of specialty construction chemical products for the local market.
- Strategic Focus: Broadening its distribution and technical service network across India, deepening relationships with contractors and project engineers, and introducing specialty product solutions tailored for infrastructure and commercial building applications.
Pidilite Industries Ltd.
Pidilite Industries Ltd. is an Indian specialty chemical company headquartered in Mumbai, India, with Dr. Fixit as its flagship construction chemicals brand and one of the most recognized names in waterproofing and construction repair solutions in the country.
- Product Portfolio: Waterproofing compounds, tile adhesives, repair mortars, construction sealants, and surface treatments under the Dr. Fixit brand.
- Recent Developments: Pidilite Industries Ltd. continues to invest in its construction chemicals business, growing its product offerings, strengthening its distribution network, and expanding applicator training and service programs across India.
- Strategic Focus: Reinforcing Dr. Fixit's market leadership by leveraging its extensive nationwide dealer and retail network, expanding waterproofing and adhesive product offerings, and investing in professional applicator certification programs to sustain brand preference across residential, commercial, and infrastructure construction.
Compagnie de Saint-Gobain S.A.
Compagnie de Saint-Gobain S.A. is a French multinational building materials company headquartered in Paris, France, operating in the India construction chemicals market through its Weber and Fosroc brands.
- Product Portfolio: Tile adhesives, leveling compounds, facade mortars, and technical rendering systems under the Weber brand; concrete admixtures, structural repair mortars, expansion joint sealants, and corrosion protection systems under the Fosroc brand.
- Recent Developments: Compagnie de Saint-Gobain S.A. continues to develop its construction chemicals business in India, integrating its product portfolio and distribution capabilities to serve a growing range of building and infrastructure construction segments.
- Strategic Focus: Accelerating its combined construction chemicals presence in India by integrating the tile adhesive and flooring strength of the Weber brand with the infrastructure admixture and structural repair capabilities of Fosroc, addressing a broader range of construction applications through unified distribution and technical service.
Market Concentration Analysis
The India construction chemicals market is moderately concentrated, with leading multinational and domestic players accounting for a significant share of organized market revenues, while a large number of regional and domestic players compete in the unorganized segment across tier-2 and tier-3 cities.
Barriers to entry include the need for substantial research and development investment in advanced chemical formulations, compliance with Bureau of Indian Standards (BIS) certification requirements, the capital intensity of manufacturing facilities, and the importance of technical service capabilities in winning project specifications. These factors favor established multinational and large domestic players with proven platform reliability and existing contractor relationships.
Consolidation is gradually increasing as larger players expand product portfolios, acquire regional distributors, and develop contractor loyalty and applicator certification programs. The ongoing transition from conventional construction materials to specialty chemical solutions in tier-2 and tier-3 cities is expected to favor organized market players over the coming years, gradually reshaping competitive dynamics.
Investment & Growth Opportunities
Fastest-Growing Segments
Waterproofing and roofing represent the fastest growing type, driven by intensifying infrastructure construction, rising awareness of long-term cost benefits among contractors, and growing adoption in large-scale real estate and hospitality projects.
Emerging Markets
East and Northeast India is the fastest-growing region, supported by accelerating urban development, expanding transport infrastructure, and increasing government investment in industrial and logistics parks.
Venture & Investment Trends
Investment activity in India's construction chemicals space is concentrated in domestic manufacturing capacity expansion, green chemistry research and development, and digital distribution platforms for construction materials. Companies are also investing in applicator training and certification programs to build brand loyalty and improve application quality, which directly supports the expansion of premium product categories and market share.
Future Market Outlook (2026-2034)
The India construction chemicals market is projected to grow from USD 2.62 Billion in 2025 to USD 2.88 Billion in 2026, reaching USD 4.76 Billion by 2034 at a CAGR of 6.49%, adding approximately USD 2.14 Billion in incremental market value over the forecast period.
Four forces will shape the market through 2034: continued large-scale infrastructure development under national programs; growing adoption of performance-enhanced and sustainable chemical formulations aligned with green building standards; deepening market penetration in tier-2 and tier-3 cities as contractor awareness and distribution networks expand; and intensifying competition driving product innovation and technical service differentiation.
By 2034, the India construction chemicals market is expected to be characterized by higher adoption of eco-friendly, polymer-modified, and nano-enhanced formulations, a more organized distribution landscape, and greater specification of specialty chemicals in affordable housing, industrial, and infrastructure construction alongside premium commercial projects.
Research Methodology
Primary Research
Primary research included structured interviews with construction chemicals manufacturers, distributors, construction contractors, architects, and project engineers, validating market sizing, segment mix, competitive landscape, and regional demand patterns.
Secondary Research
Secondary sources included Ministry of Housing and Urban Affairs publications, National Highways Authority of India reports, BIS certification data, company annual reports, investor presentations, and trade association publications from the Indian Chemical Council and Confederation of Indian Industry.
Forecasting Models
Market forecasts used top-down and bottom-up models combining construction industry output data, construction chemicals penetration rates by segment, infrastructure investment projections, and macroeconomic variables. Scenario analysis addressed infrastructure policy developments, raw material price trajectories, and construction activity growth rates.
India Construction Chemicals Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Concrete Admixtures, Waterproofing and Roofing, Repair, Flooring, Sealants and Adhesives, Others |
| Applications Covered | Residential, Non-Residential |
| Regions Covered | North India, West and Central India, South India, East and Northeast India |
| Companies Covered | Sika AG, Pidilite Industries Ltd., Compagnie de Saint-Gobain S.A., Mapei S.p.A., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India construction chemicals market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India construction chemicals market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India construction chemicals industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Construction Chemicals Market Report
The India construction chemicals market size is estimated at USD 2.88 Billion in 2026, driven by rising infrastructure investment, urbanization, and growing adoption of specialty chemical solutions across construction segments.
The market is projected to grow at a CAGR of 6.49% from 2026-2034, reaching USD 4.76 Billion, supported by infrastructure expansion and increasing construction activity.
Concrete admixtures lead the type segment at 32.8% in 2025, driven by large volumes of ready-mix concrete usage in infrastructure and high-rise construction projects.
Non-residential dominates at 62.4% in 2025, reflecting high chemical intensity of commercial buildings, industrial plants, highways, bridges, and infrastructure construction.
West and Central India commands 31.7% share in 2025, led by strong construction activity in Maharashtra and Gujarat and an established construction chemicals distribution network.
Leading players include Sika AG, Pidilite Industries Ltd., Compagnie de Saint-Gobain S.A., and Mapei S.p.A., among others.
Key drivers include rising infrastructure investments, rapid urbanization, increasing demand for high-performance concrete, growing construction activity, and the adoption of waterproofing and repair solutions to improve building durability and extend structural life.
Key challenges include raw material price volatility, fragmented distribution in tier-2 and tier-3 cities, competition from conventional materials, and inconsistent application quality in the unorganized segment.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade